 Baku 16° C
Expert calls for legal and tax reforms to develop Islamic finance in Azerbaijan
- 28 October, 2026
- 15:32
Stay up to date with the top news!
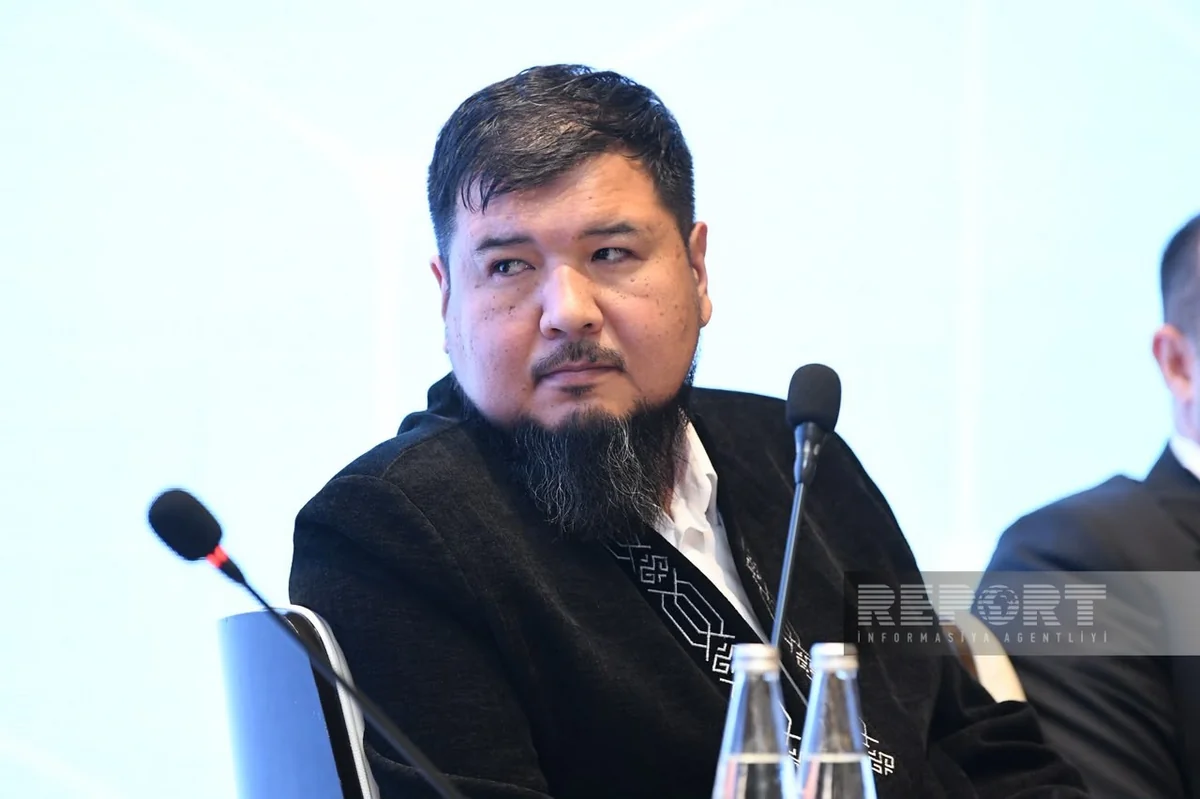
Improving the legal framework, introducing alternative financial instruments and removing tax barriers are essential to developing Islamic finance in Azerbaijan, Islamic finance expert and auditor Abdurashid Ustaz Jorayev said.
Report informs that Jorayev, who serves as chairman and member of Sharia supervisory boards, was speaking at the 12th Investment and Sustainable Development in Microfinance Conference, organized by the Azerbaijan Microfinance Association (AMFA).
In his view, Islamic finance represents a new investment segment for Azerbaijan, and its development could contribute to implementing the financial services strategy and expanding the banking and financial sector. It is important both for attracting foreign investment and mobilizing untapped domestic investment potential.
"Drawing on more than 20 years of practical experience, we have worked in various areas, from developing legislative frameworks and national strategies to promoting investment and training personnel. I propose both conventional and several unconventional steps for Azerbaijan and am ready to participate directly in their implementation.
"First, Azerbaijan needs to create alternative sources of financing. Rather than waiting for long-term, large-scale changes, new financing opportunities should be developed with support from the association of microfinance organizations and relevant institutions. Islamic financial instruments such as ijara, salam and musharaka, which have recently gained prominence, could meet emerging needs. It is also important to explore opportunities to apply these mechanisms in the microfinance sector.
"Second, a tax framework must be established and existing barriers removed. Double taxation could also impede the use of Islamic financial instruments. Therefore, amendments to the Civil Code should be reviewed first, and provisions governing the legal documentation of transactions clarified. If the Civil Code defines the legal characteristics of these transactions differently, those characteristics must also be reflected in tax legislation."
Author